
Weekly Outlook
What Happened This Week?
Global Markets
● Global economic activity remains resilient, but rising public debt and persistent inflation are creating challenges for policymakers. The U.S. economy is expanding strongly, while central banks are balancing growth against renewed price pressures.
United States
● U.S. GDP grew at an annualized rate of 3.4% in the third quarter, its strongest performance in a year and above the 3.1% expected by analysts. Growth was supported by robust consumer spending and a surge in business investment linked to AI infrastructure.
● The Federal Reserve held its benchmark rate unchanged at 3.75%–4% in a 10–2 vote, despite two officials favouring a 25-basis-point increase. Chair Kevin Warsh avoided signalling the timing of the next move, although markets broadly expect another hike in December.
● Warsh suggested that higher borrowing costs are beginning to affect AI-related investment, potentially making the sector more sensitive to monetary tightening than previously assumed. This could allow the Fed to contain demand with fewer additional rate increases.
● Fed officials have continued to comment publicly on the policy outlook despite Warsh's preference for less forward guidance. Sixteen officials made at least 59 public remarks between the previous meeting and the latest quiet period. An external task force is also preparing recommendations on how the central bank should communicate its decisions.
● The PCE price index rose 0.5% in September, lifting annual inflation to 3.6%. Core PCE increased 0.3% on the month and 3.1% over 12 months, keeping underlying price pressures above the Fed’s target.
● Personal income increased 0.2% in September, while consumer spending rose 0.5%, providing further evidence of continued household demand.
● U.S. public debt reached 100.03% of GDP at the end of fiscal 2026, its highest proportion since 1946. Publicly held debt stood at $32.2 trillion, while the budget deficit approached $2 trillion, equivalent to 6.2% of GDP.
● Consumer confidence rebounded to 91.7 in October from 84.2 in September, beating expectations of 81. However, the Conference Board cautioned that sentiment remains on a longer-term downward trend.
● Initial jobless claims fell to 194,000 in the week through October 24, below the 200,000 expected. Continuing claims also declined, dropping by 21,000 to around 1.7 million, while Fed Chair Warsh described labour-market conditions as stable.
● U.S. home prices increased 2.1% year on year in August, accelerating slightly from July’s 1.9% gain. However, inflation-adjusted home values continued to decline for a 15th consecutive month, as consumer prices rose 3.4%. Chicago recorded the strongest annual price increase among the 20 cities surveyed, followed by New York.
● The U.S. manufacturing labour market is shifting towards higher-skilled roles as automation reshapes employment. Between 2015 and 2025, the sector lost 244,000 production jobs but added 358,000 positions in management, business and financial operations. Companies are expanding training initiatives to address potential skills shortages.
Eurozone
● The European Central Bank kept interest rates unchanged as policymakers face persistent inflation risks and weaker economic momentum. The decision comes as ECB President Christine Lagarde’s successor will inherit an increasingly complex policy environment.
● Eurozone economic confidence weakened in October, with the European Commission’s indicator falling to 96.9 from 97.5 in September. Sentiment deteriorated across most sectors, with industry the only exception.
● Banks across the eurozone tightened lending standards for businesses and reported weaker demand for credit in the third quarter. The ECB attributed stricter approval conditions partly to increased risk perceptions linked to the U.S.-Iran conflict, while higher borrowing costs following earlier rate increases also weighed on loan demand.
● Ireland’s GDP expanded 5.5% in the third quarter compared with the previous quarter, offering a positive signal for regional growth despite elevated energy costs.
Germany
● German business confidence improved for a sixth consecutive month, with the Ifo index rising to 90.2 in October. The improvement came despite high energy prices and tighter financing conditions, with government plans for up to €1 trillion in defence and infrastructure investment providing support.
● Consumer sentiment moved in the opposite direction, with the GfK index slipping to -30.8 in its November forecast from -30.6 in October. Inflation reached 3.3% in September, its highest level since December 2023, largely reflecting higher energy costs.
France
● French consumer confidence fell to 80 in October, its lowest level since June 2013, according to Insee. Nationwide protests and volatility in government bonds have added to uncertainty, while consumers’ assessment of living standards dropped to its weakest level since the survey began in 1972.
United Kingdom
● Investors are looking to the upcoming U.K. budget for reassurance that the government remains committed to fiscal discipline. Prime Minister Andy Burnham and Treasury chief John Healey are expected to favour relatively moderate measures, potentially including tax increases to finance defence spending and household energy-bill support.
Canada
● Canadian wholesale sales are estimated to have increased 0.5% in September, recovering from a 1.6% decline between July and August. Higher sales of machinery, equipment, supplies and motor vehicles contributed to the expected rebound.
● The Bank of Canada raised its policy rate by 25 basis points to 2.50%, citing a significantly deteriorating inflation outlook. Governor Tiff Macklem said further tightening may be necessary, although policymakers intend to proceed cautiously.
● The central bank revised its growth projections higher, forecasting GDP expansion of 1% in 2026 and 2% in both 2027 and 2028. However, it expects headline inflation to remain above 3% through the third quarter of 2027.
Japan
● The Bank of Japan maintained its overnight call rate at 1.25%, a three-decade high, in an 8–1 vote. The central bank said underlying inflation has reached approximately 2%, marking a significant shift in the country's price environment, and forecasts economic growth of 0.7% for the current fiscal year.
Australia
● Australian inflation accelerated to 4.3% year on year in September from 4.0% in August. RBA Governor Michele Bullock warned that price pressures remain too high and demand needs to cool further.
● Markets have raised expectations of another rate increase at the RBA’s next meeting, with the probability of a hike reaching 82%. A fifth increase this year is increasingly anticipated, while some economists also see a December move as a significant risk.
New Zealand
● The Reserve Bank of New Zealand unexpectedly held its official cash rate at 2.75%, with a split 4–3 vote. Policymakers nevertheless indicated that further increases remain likely, citing global uncertainties including elevated fuel prices and the unresolved Middle East conflict.
China
● Questions are growing over the reliability of China's official growth figures, with some Western analysts estimating that the economy may be expanding at just 0%–3%, well below Beijing’s reported 4.5% third-quarter growth. Concerns also persist over limited access to economic data and restrictions on negative commentary.
Thailand
● The Bank of Thailand unanimously kept its policy rate unchanged at 1.00%. Relatively contained inflation has allowed policymakers to maintain an accommodative stance to support the country's gradual economic recovery.
This Week’s Market Movers
Forex
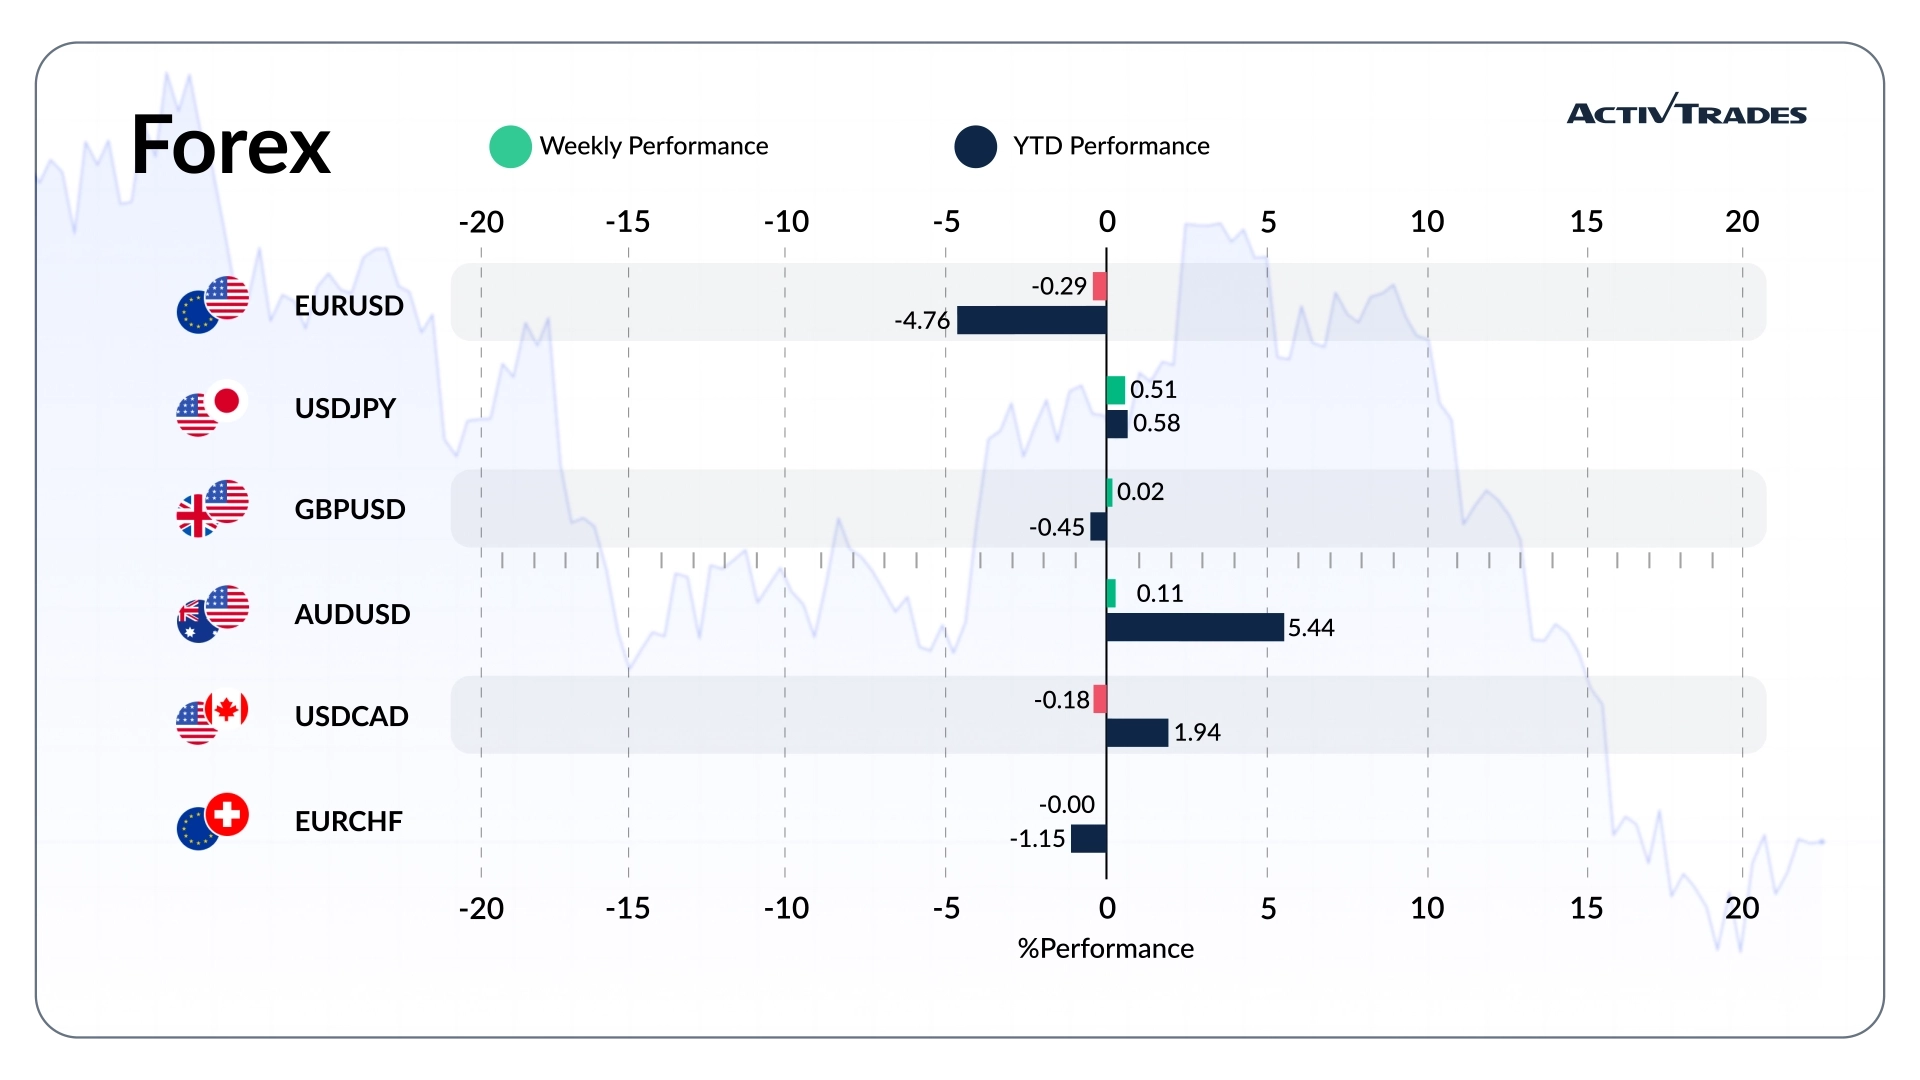
● The USD/BRL is up more than 6.5%.
● The NOK/JPY is up more than 2.2%.
● The AUD/NZD and the CAD/NZD are up more than 1.1%.
● The GBP/NZD and the CAD/JPY are up more than 0.8%.
● The USD/JPY is up more than 0.5%.
● The USD/CHF is up more than 0.4%.
● The CHF/NOK and the EUR/NOK are down more than 1.3%.
● The NZD/USD is down more than 0.8%.
● The JPY/AUD is down more than 0.7%.
Commodities
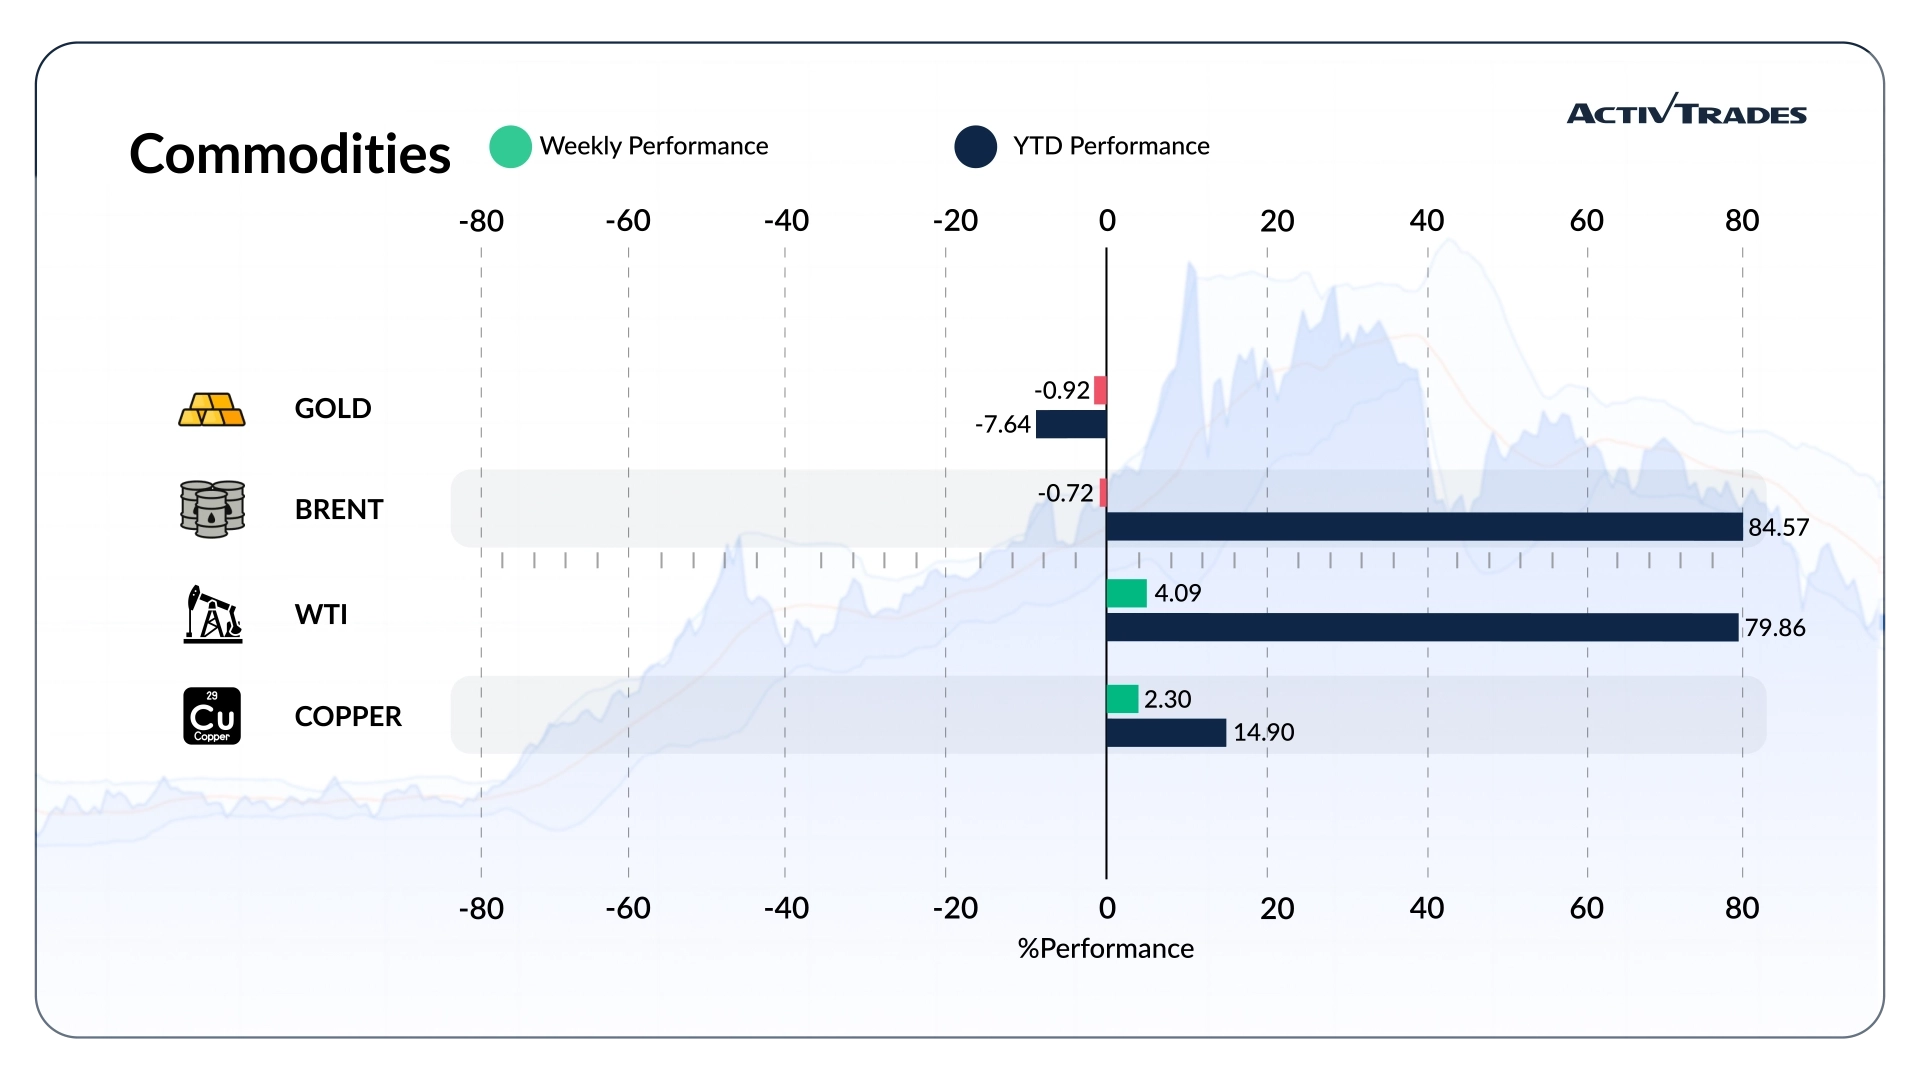
● Natural Gas prices are up more than 9.7%.
● Dutch TTF Natural Gas prices are up more than 7.1%.
● Zinc prices are up more than 3.3%.
● Lean Hogs prices are down more than 8.4%.
● Platinum prices are down more than 7.6%.
● US Coffee and Palladium prices are down more than 6.3%.
● Silver prices are down more than 5.6%.
Indices
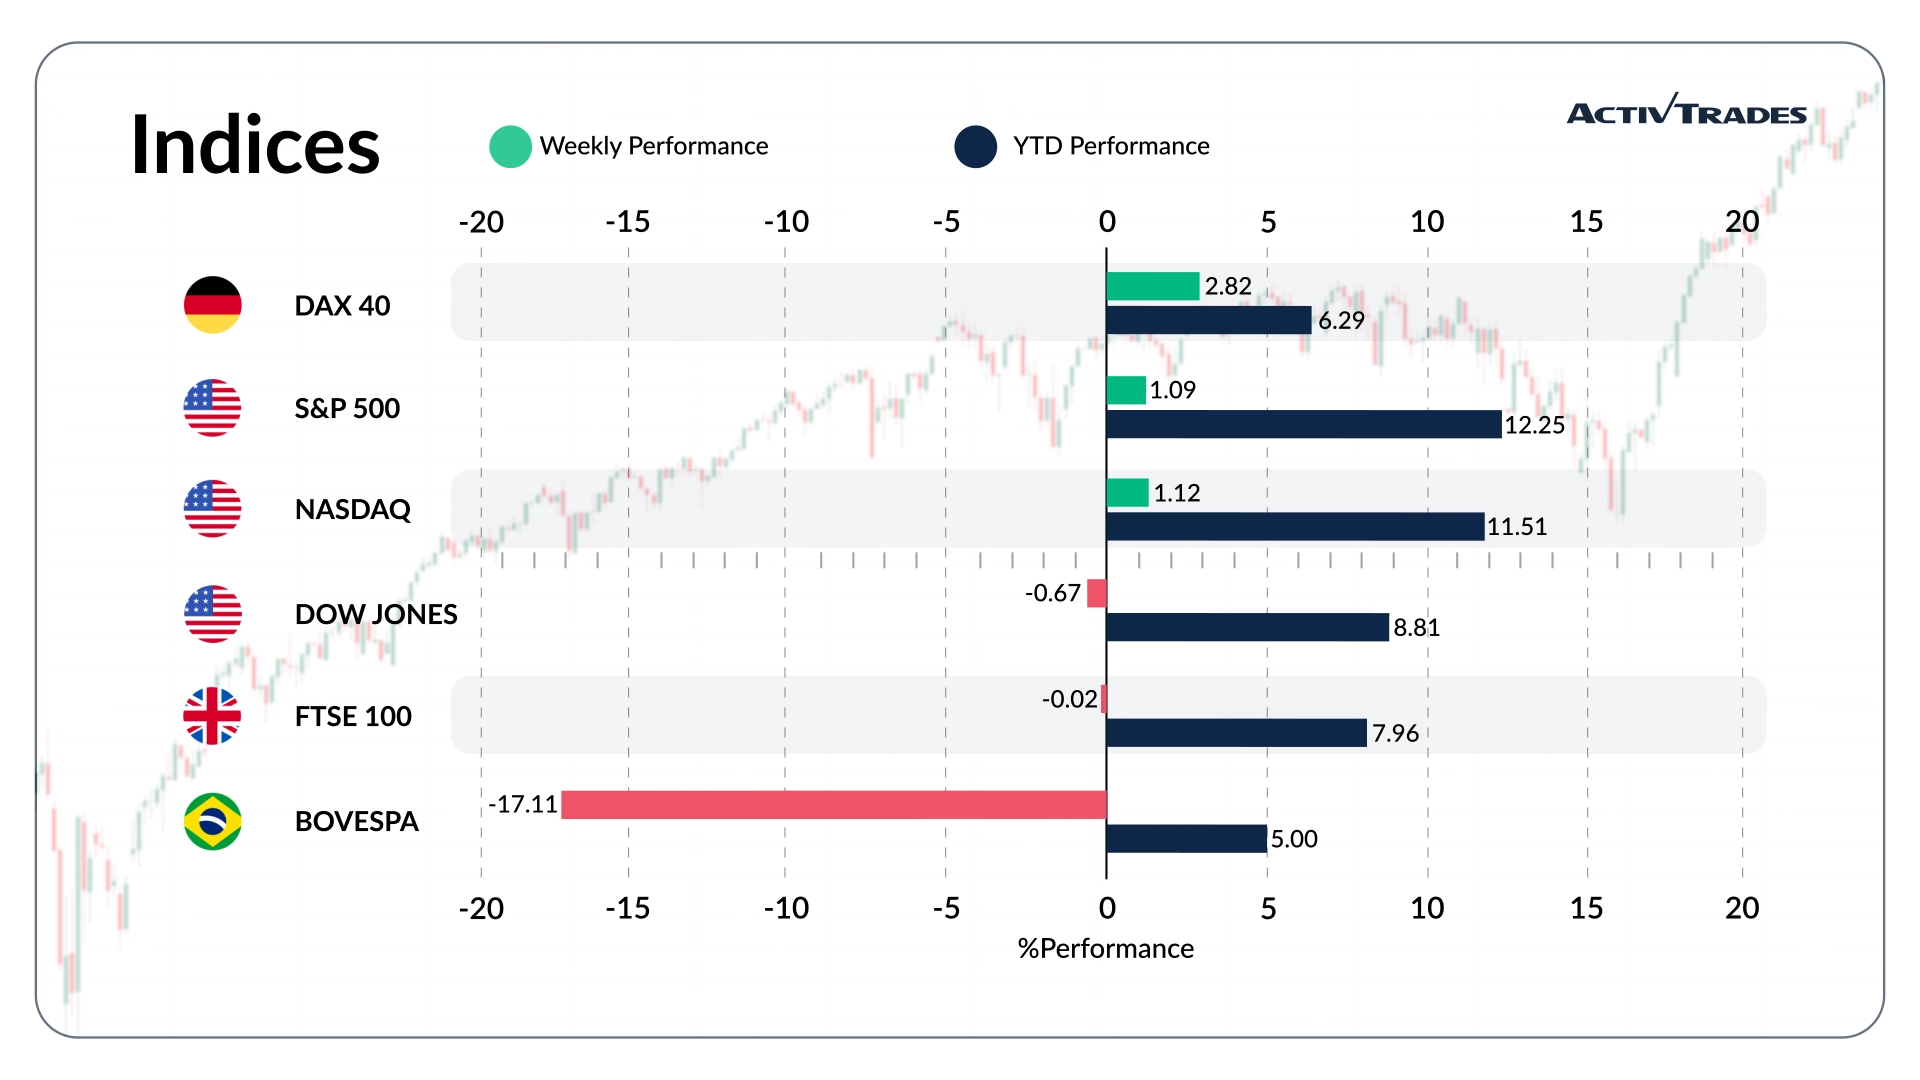
● The Kospi index is up more than 6%.
● The DAX index is up more than 2.1%.
● The Bovespa index is down more than 18%.
● The IDX Composite index is down more than 6.7%.
● The VIX index is down more than 5.9%.
● The IDX 30 index is down more than 5.6%.
● The Bist100 index is down more than 4.8%.
Shares
Tops
● Lumentum: +22.19%
● Pentair: +18.76%
● Norwegian Cruise Line: +17.25%
● Carvana: +16.33%
● Synopsys: +16.03%
● Ferrovial: +15.42%
● Rocket Lab: +15.38%
● Quanta Services: +14.98%
● KLA: +13.26%
● Astera Labs: +12.65%
● Siemens: +11.52%
● Deutsche Bank: +11.25%
● Stellantis: +11.24%
● STMicroelectronics: +10.62%
Flops
● Servicenow: -30.15%
● Alnylam Pharmaceuticals: -23.44%
● Costar: -20.62%
● Fortinet: -19.59%
● F5: -19.25%
● Kering: -17.43%
● Xylem: -16.93%
● Cognizant Technology Solutions: -15.19%
● Fair Isaac: -13.86%
● Alphabet: -12.46%
● Symrise: -10.30%
Important Events to Follow
Monday 02 November
● 01:45 AM - Chinese - RatingDog Manufacturing PMI (October)
○ Previous: 52.1
○ Forecast: 51.5
● 08:15 AM - Spanish - S&P Global Manufacturing PMI (October)
○ Previous: 51.0
○ Forecast: 50.7
● 08:30 AM - Swiss - procure.ch Manufacturing PMI (October)
○ Previous: 55.3
● 08:50 AM - French - S&P Global Manufacturing PMI Final (October)
○ Previous: 50.6
○ Forecast: 49.3
● 08:55 AM - German - S&P Global Manufacturing PMI Final (October)
○ Previous: 53.9
○ Forecast: 54.2
● 09:00 AM - European - S&P Global Manufacturing PMI Final (October)
○ Previous: 52.9
○ Forecast: 52.4
● 09:30 AM - UK - S&P Global Manufacturing PMI Final (October)
○ Previous: 51.9
○ Forecast: 52.8
● 02:00 PM - American - ISM Manufacturing PMI (October)
○ Previous: 54.5
○ Forecast: 54.7
● 02:30 PM - Canadian - S&P Global Manufacturing PMI (October)
○ Previous: 51.5
○ Forecast: 51
Tuesday 03 November
● 03:30 AM - Australian - RBA Interest Rate Decision
○ Previous: 4.6%
○ Forecast: 4.85%
● 02:45 PM - American - S&P Global Manufacturing PMI Final (October)
○ Previous: 55.9
○ Forecast: 56
● 03:00 PM - American - JOLTs Job Openings (September)
○ Previous: 7.079M
○ Forecast: 7.06M
● 10:00 PM - Australian - S&P Global Composite PMI Final (October)
○ Previous: 51.3
○ Forecast: 47.7
● 10:00 PM - Australian - S&P Global Services PMI Final (October)
○ Previous: 51.9
○ Forecast: 47.8
Wednesday 04 November
● 01:45 AM - Chinese - RatingDog Services PMI (October)
○ Previous: 51.6
○ Forecast: 51.5
● 01:45 AM - Chinese - RatingDog Composite PMI (October)
○ Previous: 52.4
○ Forecast: 52.2
● 08:15 AM - Spanish - S&P Global Services PMI (October)
○ Previous: 58.3
○ Forecast: 57.5
● 08:15 AM - Spanish - S&P Global Composite PMI (October)
○ Previous: 56.8
○ Forecast: 56
● 08:50 AM - French - S&P Global Composite PMI Final (October)
○ Previous: 51.1
○ Forecast: 48.4
● 08:50 AM - French - S&P Global Services PMI Final (October)
○ Previous: 51.2
○ Forecast: 48.4
● 08:55 AM - German - S&P Global Composite PMI Final (October)
○ Previous: 53.8
○ Forecast: 52.8
● 08:55 AM - German - S&P Global Services PMI Final (October)
○ Previous: 52.9
○ Forecast: 51.7
● 09:00 AM - European - S&P Global Composite PMI Final (October)
○ Previous: 53.1
○ Forecast: 51.9
● 09:00 AM - European - S&P Global Services PMI Final (October)
○ Previous: 53.0
○ Forecast: 51.7
● 09:30 AM - UK - S&P Global Composite PMI Final (October)
○ Previous: 52.0
○ Forecast: 53.1
● 09:30 AM - UK - S&P Global Services PMI Final (October)
○ Previous: 52.1
○ Forecast: 53.1
● 10:00 AM - European - Inflation Rate YoY Flash (October)
○ Previous: 3.8%
○ Forecast: 3.8%
● 02:00 PM - American - ISM Services PMI (October)
○ Previous: 54.9
○ Forecast: 54.5
● 02:30 PM - Canadian - S&P Global Composite PMI (October)
○ Previous: 48.7
○ Forecast: 48.5
● 02:30 PM - Canadian - S&P Global Services PMI (October)
○ Previous: 48.3
○ Forecast: 48.4
● 02:45 PM - American - S&P Global Composite PMI Final (October)
○ Previous: 58.4
○ Forecast: 57.6
● 02:45 PM - American - S&P Global Services PMI Final (October)
○ Previous: 58.8
○ Forecast: 57.9
Thursday 05 November
● 12:30 AM - Australian - Balance of Trade (September)
○ Previous: A$0.495B
○ Forecast: A$0.7B
● 12:30 AM - Japanese - S&P Global Manufacturing PMI Final (October)
○ Previous: 54.1
○ Forecast: 53.3
● 08:30 AM - European - S&P Global Construction PMI (October)
○ Previous: 43.4
○ Forecast: 44
● 08:30 AM - French - S&P Global Construction PMI (October)
○ Previous: 39.8
○ Forecast: 41
● 08:30 AM - German - S&P Global Construction PMI (October)
○ Previous: 43.5
○ Forecast: 44
● 09:30 AM - UK - S&P Global Construction PMI (October)
○ Previous: 46.1
○ Forecast: 45.5
● 12:00 PM - UK - BoE Interest Rate Decision
○ Previous: 3.75%
○ Forecast: 4%
Friday 06 November
● 12:30 AM - Japanese - S&P Global Composite PMI Final (October)
○ Previous: 52.3
○ Forecast: 52.3
● 12:30 AM - Japanese - S&P Global Services PMI Final (October)
○ Previous: 51.3
○ Forecast: 52.0
● 01:30 PM - Canadian - Unemployment Rate (October)
○ Previous: 6.5%
○ Forecast: 6.5%
● 01:30 PM - American - Non Farm Payrolls (October)
○ Previous: 29K
○ Forecast: 40.0K
● 01:30 PM - American - Unemployment Rate (October)
○ Previous: 4.2%
○ Forecast: 4.2%
● 03:00 PM - Canadian - Ivey PMI s.a (October)
○ Previous: 58.2
○ Forecast: 57.5
● 03:00 PM - American - Michigan Consumer Sentiment Prel (November)
○ Previous: 48.0
○ Forecast: 47.0
Major Earnings Reports to Watch
Monday 02 November
● APPLE
● Loews Corporation
● Vertex Pharmaceuticals
Tuesday 03 November
● Booking
● KONINKLIJKE
● Electronic Arts
● CTT CORREIOS PORT
● COMPASS
● Ferrari
● Amgen
● PFIZER
● Marathon Petroleum
● AMD
● Fresenius Medical Care AG & Co
● Hugo Boss
● BioNTech
● Deutsche Lufthansa
● Zalando
● Super Micro Computer
● NOS
● Bayer
● AIG
Wednesday 04 November
● Uber Technologies
● MCDONALDS
● Kraft Heinz
● CVS Health
● Western Union
● Qualcomm
● Arm
● Solvay
● HeidelbergCement
● BMW
● Semapa-Sociedade De Investim
● Continental
● Beyond Meat
● Novo Nordisk
● Tenaris
● Fresenius SE & Co
● McKesson
● Expedia
Thursday 05 November
● Mattel
● EDP Renovaveis
● LEGRAND
● Chesapeake
● Air France-KLM
● Bouygues
● Cellnex Telecom
● ENGIE
● Sony
● Rockwell Automation
● Toyota Motor
● DHL
● Novavax
● ConocoPhillips
● Swiss Re
● Rheinmetall
● Commerzbank
● Deutsche Telekom
● AAON
● NATIONAL GRID
Friday 06 November
● Moderna
● Energias De Portugal
● Daimler
● Canopy Growth
Source: The Wall Street Journal, Investing, Trading Economics Calendar GMT, Reuters, TradingView and ActivTrades’ Data as of October 30, 2026
The information provided does not constitute investment research. The material has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and as such is to be considered to be a marketing communication.
All information has been prepared by ActivTrades (“AT”). The information does not contain a record of AT’s prices, or an offer of or solicitation for a transaction in any financial instrument. No representation or warranty is given as to the accuracy or completeness of this information.
Any material provided does not have regard to the specific investment objective and financial situation of any person who may receive it. Past performance is not a reliable indicator of future performance. AT provides an execution-only service. Consequently, any person acting on the information provided does so at their own risk. Forecasts are not guarantees. Rates may change. Political risk is unpredictable. Central bank actions may vary. Platforms’ tools do not guarantee success.