
Weekly Outlook
What Happened This Week?
United States
- The Fed raised its target rate to 3.75%-4.00%, with officials signalling that further tightening could follow as inflation remains elevated.
- Fed Chair Kevin Warsh said the economy and labour market remain strong enough to support higher rates, while indicating that the latest hike could be the start of a broader anti-inflation campaign.
- U.S. jobless claims fell by 10,000 to 196,000 in the week through September 12, while continuing claims dropped to 1.73 million, pointing to continued labour-market resilience.
- U.S. retail sales rebounded 1.2% in August to $773.9 billion, above the 0.8% expected, with GDP-related control-group sales increasing around 1.4%.
- The New York Fed manufacturing index fell sharply to 7.6 in September from 20.6 in August, missing expectations, while price pressures intensified.
- U.S. housing starts declined 2.6% in August to 1.275 million, while building permits fell 2.7%, adding to signs of pressure on the housing sector.
- U.S. mortgage rates are approaching 7%, their highest level since January 2025, potentially weighing further on housing demand and construction.
- Higher energy costs are creating a dilemma for U.S. companies, with some raising prices while others are cutting prices to protect market share.
Europe
- The Bank of England held its key rate at 3.75%, but three of nine policymakers voted for a hike to 4%, keeping the possibility of further tightening alive as energy costs fuel inflation.
- U.K. inflation accelerated to 3.1% in August from 2.9% in July, driven by household energy, petrol and diesel prices, air fares and factory-gate costs.
- U.K. unemployment remained at 4.9% in the three months through July, close to a five-year high, while annual wage growth excluding bonuses held at 3.5%.
- Eurozone industrial production declined 0.1% in July, following a similar fall in June, with Germany and France recording declines of 1.5% and 0.4%, respectively.
- The weakness in industrial output contrasts with improving manufacturer confidence, with activity reportedly expanding at its fastest pace in more than four years in August.
Japan
- The Bank of Japan raised its benchmark rate to 1.25%, its highest level in 30 years, while signalling that further increases could follow.
- Higher Japanese rates could encourage domestic investors to repatriate capital, with Japanese investors holding around $2.5 trillion in U.S. financial assets.
- A shift in Japanese capital flows could therefore have implications for U.S. Treasuries and broader global markets.
Australia
- RBA Governor Michele Bullock warned that persistent inflation pressures are materialising, with capacity constraints and the Middle East conflict expected to keep inflation elevated.
- Markets are pricing in a near-certain RBA rate increase later this month.
Canada
- The Bank of Canada kept its benchmark rate at 2.25%, while policymakers acknowledged that higher fuel costs could require further rate hikes if they spread into broader prices.
- Officials also warned that higher tariffs on Canadian goods could weaken the emerging economic recovery.
- Canadian inflation held at 3% in August, while core inflation excluding gasoline accelerated to 2.4% from 2.2%.
- Canadian industrial producer prices rose 1.3% in July, above expectations, while raw-material prices increased 3.1% in August and were 22.8% higher year-on-year.
- Canadian housing starts slipped 0.1% in August, while existing-home sales fell 0.7%, adding to signs of a slowing property market.
Asia-Pacific
- Taiwan’s central bank kept its discount rate unchanged at 2% for a 10th consecutive quarter, supported by strong AI-related economic growth despite inflation moving above its 2% warning threshold.
- China’s financial and economic outlook remains influenced by global energy costs and shifting inflation pressures.
- The World Bank mobilised $112 billion in private capital alongside $123 billion of its own financing, highlighting the growing role of private investment in global development funding.
Global Markets
- The WTO warned that increasing fragmentation of global trade into geopolitical blocs could weigh significantly on long-term growth.
- The organisation estimates that a bloc-based trading system could reduce global exports by 18.6% and global economic output by 5.1% by 2050.
- Around 72% of global goods trade remains compatible with non-discriminatory WTO rules, down from 80%.
- Higher energy prices remain a key cross-market risk, influencing inflation expectations, central-bank policy and government bond yields.
This Week’s Market Movers
Forex
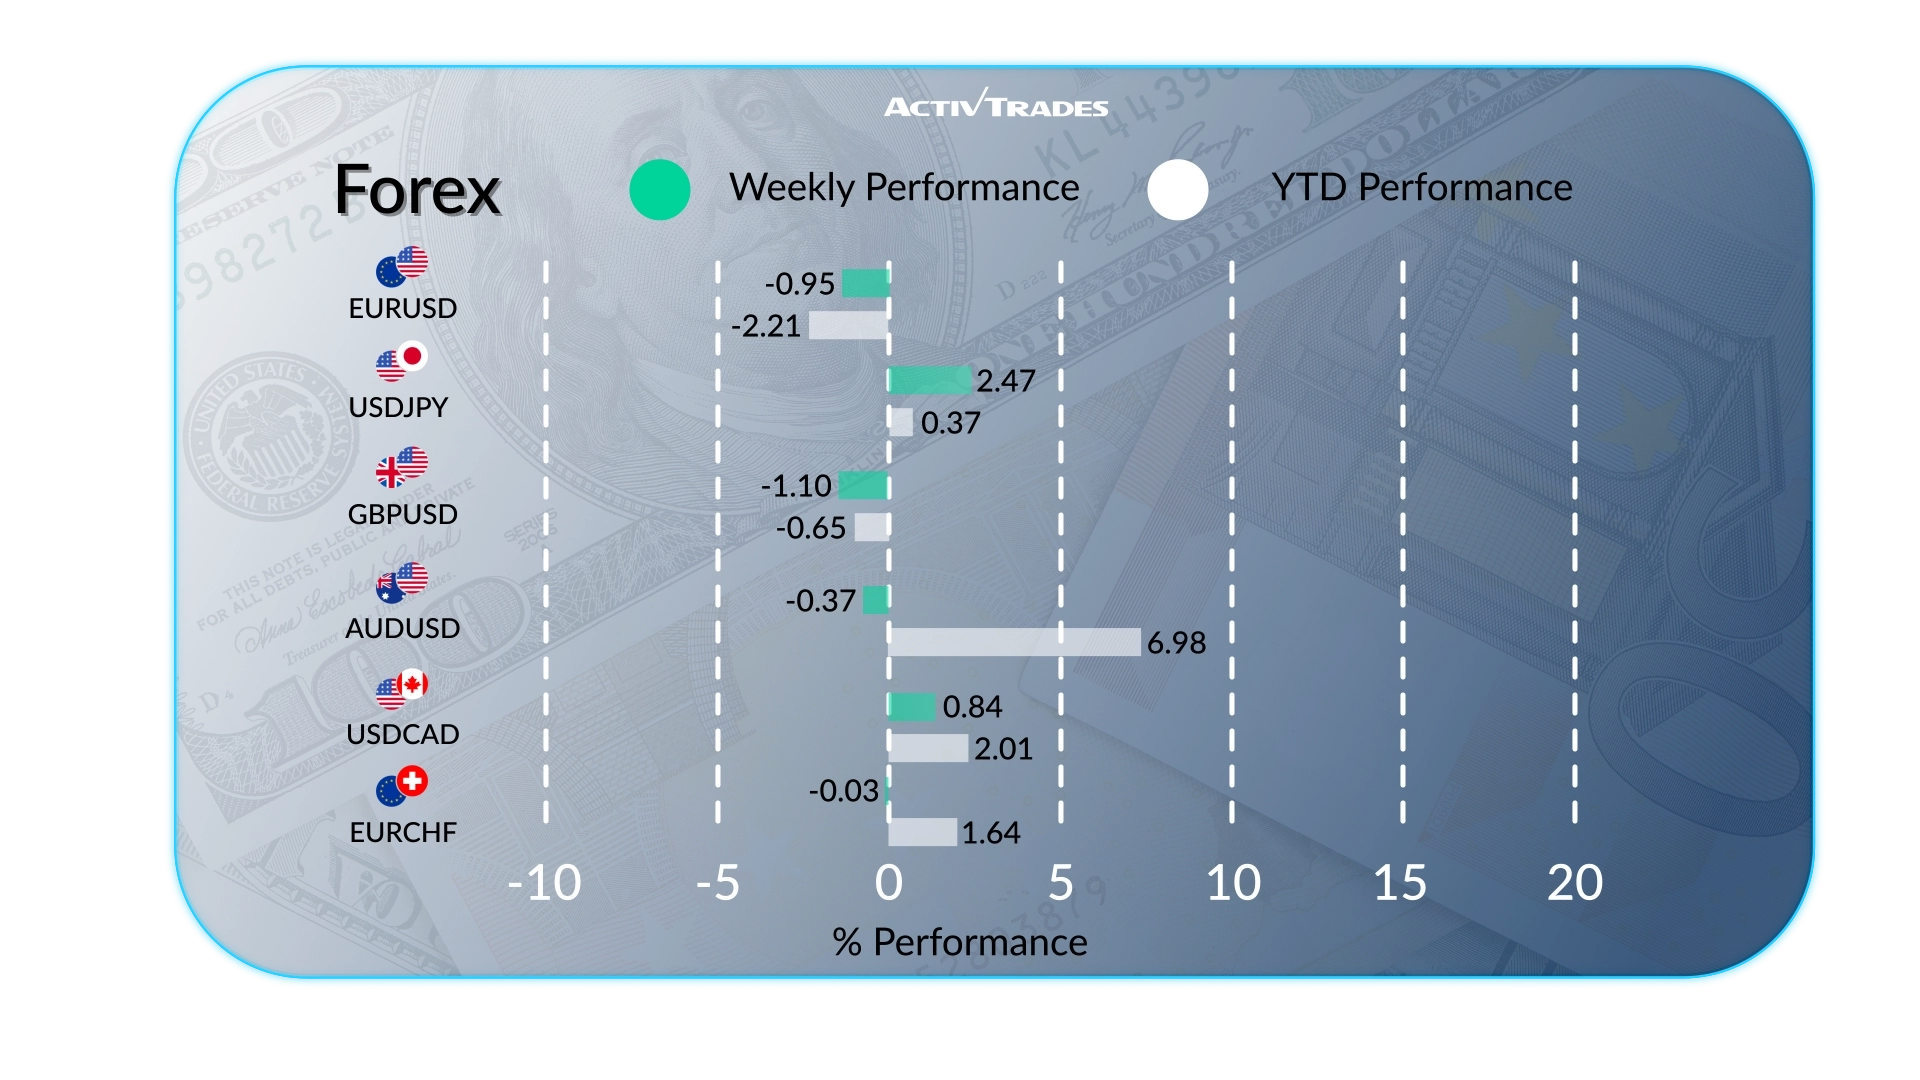
- The USD/JPY, the HKD/JPY and the USD/PLN are up more than 1.9%.
- The ZAR/JPY is up more than 1.7%.
- The AUD/JPY is up more than 1.5%.
- The USD/CHF is up more than 1.4%.
- The AUD/CHF is up more than 0.9%.
- The CHF/HKD and the NZD/HKD are down more than 1.2%.
- The NZD/USD and the EUR/USD are down more than 1.1%..
Commodities
Indices
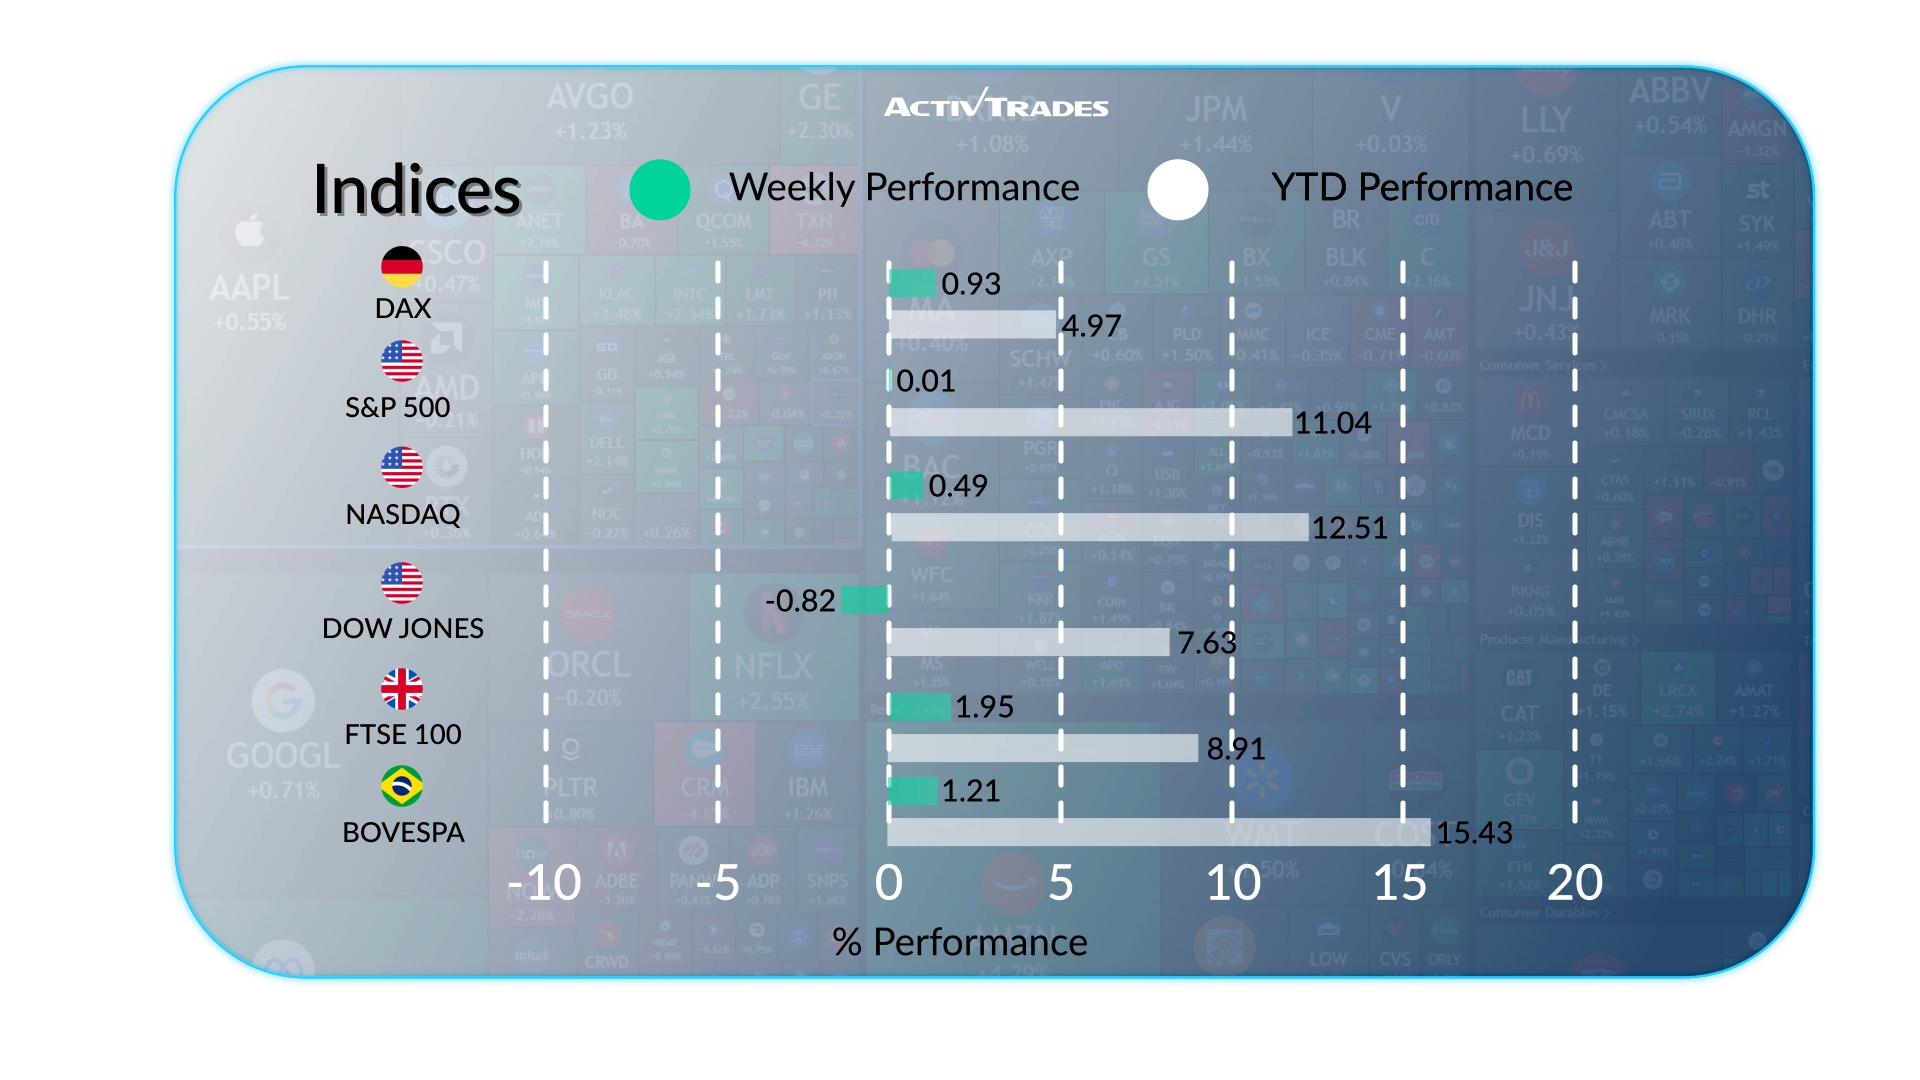
- The Nasdaq index is up more than 1.5%.
- The Japan 225, the UK 100 and the Kospi indices are up more than 1.3%.
- The Bist100 index is down more than 7%.
- The VIX index is down more than 5.3%.
Shares
Tops
- Revvity: +21.32%
- Crowdstrike: +17.64%
- Dell Technologies: +16.14%
- Moderna: +15.70%
- Generac: +14.07%
Alexandria Real Estate Equities: +13.68%
Flops
- JB Hunt Transport Services: -11.53%
- Coreweave: -10.37%
Important Events to Follow
Tuesday 22 September
- 11:00 PM - Australian - S&P Global Manufacturing PMI Flash (September)
- Previous: 52.0
- Forecast: 51.7
- 11:00 PM - Australian - S&P Global Services PMI Flash (September)
- Previous: 53.2
- Forecast: 52.5
- 11:00 PM - Australian - S&P Global Composite PMI Flash (September)
- Previous: 52.7
- Forecast: 52
Wednesday 23 September
- 07:15 AM - French - S&P Global Composite PMI Flash (September)
- Previous: 48.5
- Forecast: 49.1
- 07:15 AM - French - S&P Global Manufacturing PMI Flash (September)
- Previous: 51.1
- Forecast: 51
- 07:15 AM - French - S&P Global Services PMI Flash (September)
- Previous: 48.0
- Forecast: 49.1
- 07:30 AM - German - S&P Global Manufacturing PMI Flash (September)
- Previous: 54.3
- Forecast: 53.6
- 07:30 AM - German - S&P Global Composite PMI Flash (September)
- Previous: 51.8
- Forecast: 51.7
- 07:30 AM - German - S&P Global Services PMI Flash (September)
- Previous: 49.7
- Forecast: 50.5
- 08:00 AM - European - S&P Global Composite PMI Flash (September)
- Previous: 52.0
- Forecast: 51.7
- 08:00 AM - European - S&P Global Manufacturing PMI Flash (September)
- Previous: 52.7
- Forecast: 52.7
- 08:00 AM - European - S&P Global Services PMI Flash (September)
- Previous: 51.6
- Forecast: 51.5
- 08:30 AM - UK - S&P Global Manufacturing PMI Flash (September)
- Previous: 51.7
- Forecast: 51.7
- 08:30 AM - UK - S&P Global Services PMI Flash (September)
- Previous: 52.5
- Forecast: 52.6
- 08:30 AM - UK - S&P Global Composite PMI Flash (September)
- Previous: 52.5
- Forecast: 52.3
- 01:45 PM - American - S&P Global Composite PMI Flash (September)
- Previous: 56
- Forecast: 55.2
- 01:45 PM - American - S&P Global Manufacturing PMI Flash (September)
- Previous: 53.9
- Forecast: 53
- 01:45 PM - American - S&P Global Services PMI Flash (September)
- Previous: 56.5
- Forecast: 56.4
Thursday 24 September
- KoPrevious: 54.9
- Forecast: 54
- 12:30 AM - Japanese - S&P Global Services PMI Flash (September)
- Previous: 52.5
- Forecast: 52
- 12:30 AM - Japanese - S&P Global Composite PMI Flash (September)
- Previous: 53.5
- Forecast: 52.7
- 08:00 AM - German - Ifo Business Climate (September)
- Previous: 88.8
- Forecast: 87.9
Friday 25 September
- 06:00 AM - German - GfK Consumer Confidence (October)
- Previous: -26.6
- Forecast: -27.4
- 12:30 PM - American - Durable Goods Orders MoM (August)
- Previous: 1.1%
- Forecast: 0.5%
Major Earnings Reports to Watch
Wednesday 23 September
- General Mills
Thursday 24 September
- Costco
Source: The Wall Street Journal, Investing, Trading Economics Calendar GMT, Reuters, TradingView and ActivTrades’ Data as of September 18, 2026
The information provided does not constitute investment research. The material has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and as such is to be considered to be a marketing communication.
All information has been prepared by ActivTrades (“AT”). The information does not contain a record of AT’s prices, or an offer of or solicitation for a transaction in any financial instrument. No representation or warranty is given as to the accuracy or completeness of this information.
Any material provided does not have regard to the specific investment objective and financial situation of any person who may receive it. Past performance is not a reliable indicator of future performance. AT provides an execution-only service. Consequently, any person acting on the information provided does so at their own risk. Forecasts are not guarantees. Rates may change. Political risk is unpredictable. Central bank actions may vary. Platforms’ tools do not guarantee success.